If you have been sitting on the fence about buying a home in Kenya, waiting for the right moment, that moment is now. Absa Bank Kenya has just launched a home financing solution that quietly redraws the map for what is possible when it comes to homeownership in this country. And when you stack it up against what the rest of the market is offering, the case becomes even more compelling.
Let us start with the headline number. Absa is offering a home loan rate of 8.9% per annum. To understand why that matters, you need to know what the lending landscape looks like right now. The average bank lending rate in Kenya sits at around 14.81%, and most commercial banks are offering mortgage rates somewhere between 13.5% and 18%. Co-operative Bank is at roughly 13.75%, and KCB and HF Group have been among the lower end at 13.5%. KCB has also been running a promotional campaign at 8.9% fixed, but that is a time-limited offer running only until September 2026, tied to specific conditions including checkoff salary arrangements. Absa’s 8.9% rate comes as part of a structured developer-linked product that is designed to be a long-term financing solution, not a short window to rush through. Mortgage
What makes Absa’s offering particularly interesting is the 105% financing option for qualifying buyers. That means you could potentially finance not just the full cost of a property but also some of the associated costs, stamp duty, legal fees, and other purchase expenses, without having to drain your savings before you even move in. For most Kenyans, it is the upfront costs that kill the dream of homeownership before it even begins. Being able to roll those into the loan changes the calculation entirely.
The product is structured around what Absa calls a developer off-taker proposition. In plain language, this means Absa is connecting buyers directly with property developers early in the construction cycle, rather than waiting until a project is complete. This matters more than it might seem at first glance. When you buy off-plan through a bank-approved developer partnership, you typically get better pricing, more flexible payment structures, and the financial benefit of property appreciation during the construction period. For developers, it means they have committed buyers from the outset, which reduces project risk and improves delivery timelines. For you as the buyer, it means you get a seat at the table before the best units are taken.
Kenya’s housing crisis gives all of this context. The country faces a deficit of over two million housing units. Annual housing demand is estimated at around 250,000 households, but fewer than 50,000 units are being delivered each year. That gap is not closing anytime soon, and every year you delay a purchase decision, you are competing against a market where demand will continue to far outstrip supply. Property prices in Nairobi and other urban centres have been appreciating steadily, and analysts suggest that the opportunity cost of waiting, in terms of price increases alone, can easily exceed the cost of borrowing.
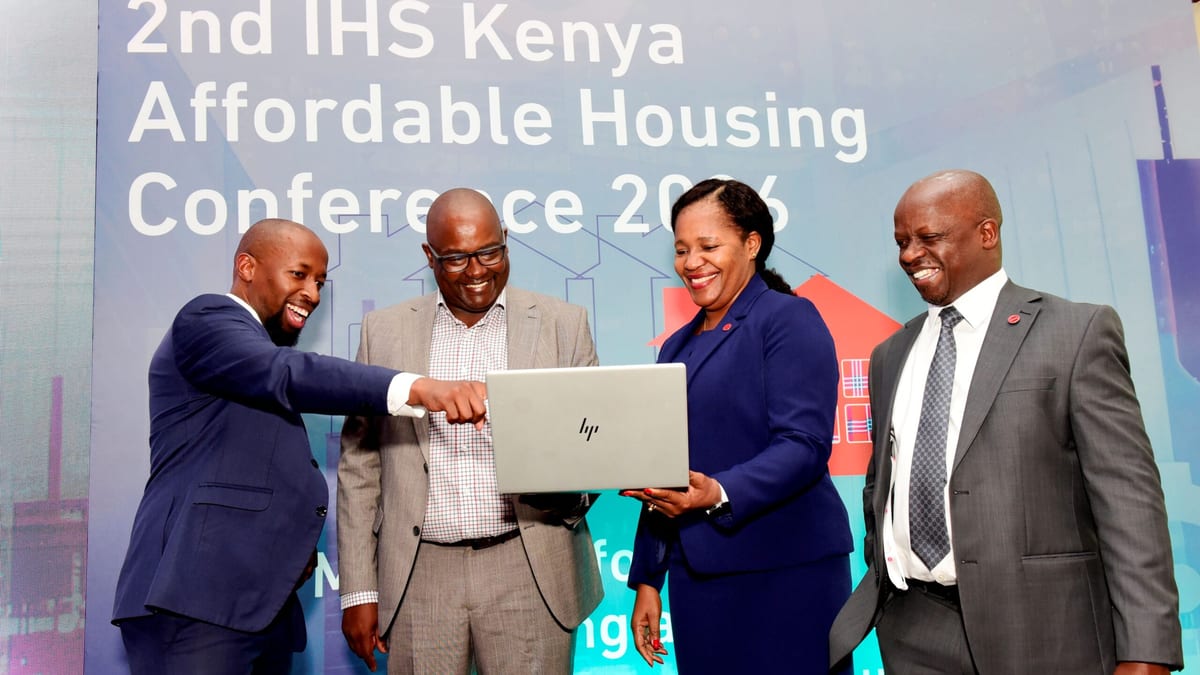
James Agin, Absa Bank Kenya’s Managing Executive for Corporate and Investment Banking, put the structural problem plainly at the International Housing Solutions Kenya Affordable Housing Conference 2026. He pointed out that a significant portion of Kenya’s market earns outside traditional formal employment frameworks, yet most financing models are built around predictable, salaried income. The disconnect between how people actually earn money, how housing projects get funded, and how properties are priced has been the real bottleneck. Absa’s developer-linked model is a direct attempt to address this by creating a more flexible pathway to ownership that brings buyers, developers, and financiers together from the beginning of a project rather than at the end.
The mortgage pre-assessment during construction is another feature worth noting. Rather than scrambling to arrange financing once a building is complete, qualifying buyers under this programme can have their mortgage eligibility assessed while the property is still being built. Combined with negotiated legal and valuation support, this streamlines what is traditionally one of the most stressful and drawn-out processes in any homebuying journey.
Kenya’s Central Bank Rate has come down significantly following nine consecutive rate cuts, and the economic environment in 2026, with GDP growth projected at 5.5% and a stable shilling, is arguably the most favourable lending environment the country has seen in years. That broader easing cycle is what has made sub-10% mortgage rates possible at all, and there is no guarantee that conditions will remain this accommodating. Rates can and do move upward, and locking in a competitive rate now is a hedge against future uncertainty. Soko Mix
For Kenyans in the diaspora, Absa also has mortgage products tailored to those buying from abroad, meaning the opportunity is not limited to those currently on the ground in Kenya.
The bottom line is straightforward. The combination of an 8.9% per annum rate, up to 105% financing, early developer access, streamlined processing, and a housing market that is only going to get more competitive makes this one of the most genuinely attractive home financing propositions Kenya has seen. Whether you are a first-time buyer, someone looking to upgrade, or an investor seeking to secure property in an undersupplied market, Absa Bank’s new home loan offering deserves a serious look. The right moment to act on homeownership in Kenya is not some distant point in the future. It is right now.