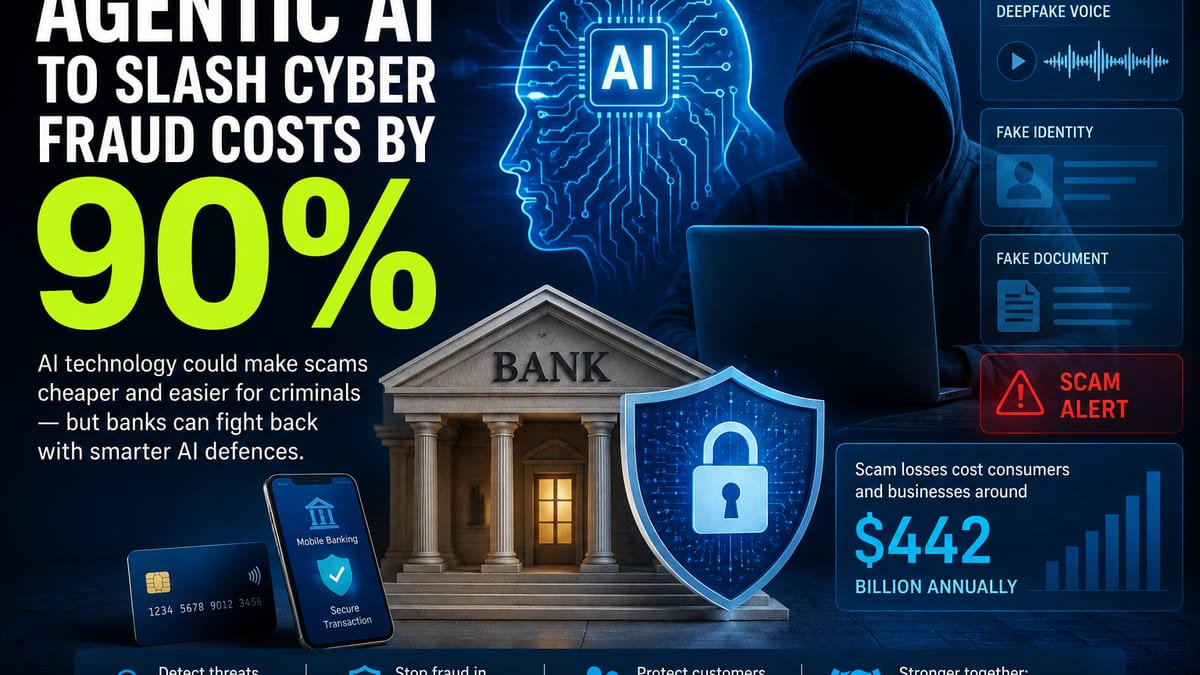
Agentic AI to slash cyber fraud costs by 90% could make it much easier and cheaper for criminals to launch sophisticated online scams, according to Boston Consulting Group (BCG). While this technology poses a serious threat, experts say banks can also use artificial intelligence (AI) to better protect customers and prevent fraud.
Generative AI is already changing the way cybercriminals operate. Criminals can now create fake identities, clone people’s voices, produce realistic documents, and even use deepfake videos to trick victims. As these tools become more advanced, it will become harder for people and banks to tell what is real and what is fake.
Africa faces a growing challenge because more people are using mobile banking and digital payment services every day. While these services have improved financial inclusion, they have also created more opportunities for scammers to target consumers and businesses.
Recent data shows that online fraud is becoming more organised across Africa. According to TransUnion’s H1 2026 Fraud Trends Report, criminals are increasingly targeting digital identities. In Kenya, the average amount lost by fraud victims reached KSh108,482, while South Africa recorded high levels of suspicious login attempts.
BCG warns that the next major threat will come from agentic AI—AI systems capable of planning and carrying out scams with little or no human involvement. These systems could automate the entire fraud process, from identifying victims to stealing money.
Experts estimate that agentic AI could reduce the cost of carrying out scams by more than 90%, allowing criminals to launch far more attacks, test different methods, and quickly adjust when banks strengthen their security.
Toivo Hensgens, Partner at BCG Nairobi, says Kenya is especially vulnerable because millions of people rely on mobile money and digital banking every day. If scammers begin using agentic AI, they could launch highly personalised attacks on a much larger scale, leading to greater financial losses and reducing public trust in digital financial services.
However, Hensgens says AI is not only a threat—it is also one of the strongest tools banks can use to fight fraud. Banks can use AI to detect suspicious behaviour earlier, stop fraudulent transactions in real time, and respond much faster to new cyber threats.
Financial fraud is becoming more expensive
Financial scams already cost consumers and businesses around US$442 billion every year, according to the Global Anti-Scam Alliance.
Scammers often convince people to willingly send money or trick them into revealing personal information that gives criminals access to their bank accounts. As digital fraud becomes more advanced, banks also face higher operational costs through customer complaints, investigations, disputes, and regulatory pressure.
This growing threat makes it more important than ever for banks to strengthen their fraud prevention systems before agentic AI becomes widely available.
Banks still have time to prepare
BCG believes banks have a small window of opportunity before powerful open-source AI models become widely available to criminals.
The consulting firm has already worked with several financial institutions across Africa to improve fraud detection using AI, behavioural analysis, and advanced data analytics. These banks have been able to identify suspicious activity earlier, reduce pressure on fraud investigation teams, and respond more quickly to emerging threats.
Henok Eyob, Managing Director and Partner at BCG Nairobi, says Kenya’s success in digital financial services makes stronger cybersecurity even more important. He says banks that invest in AI-powered fraud prevention today will be better prepared than those that wait until attacks become more widespread.
Five ways banks can prepare
BCG recommends that banks take the following steps:
- Improve threat monitoring by collecting better data and constantly updating AI systems to detect new scam techniques.
- Invest in advanced AI technology and build skilled internal AI teams that can quickly deploy new security tools.
- Create flexible operating systems that can respond rapidly when fraud attempts increase suddenly.
- Work closely with partners such as telecom companies, payment providers, social media platforms, regulators, and law enforcement agencies to identify and stop scams faster.
- Develop emergency response plans so banks can quickly introduce extra security measures during periods of unusually high fraud activity.
The future of banking security
BCG believes the move to AI-powered scams may happen much faster than many organisations expect. As cybercriminals adopt smarter AI tools, traditional fraud prevention methods may no longer be enough.
Banks that invest now in AI-driven fraud detection, real-time monitoring, and stronger collaboration across the financial sector will be in a better position to protect customers, reduce financial losses, and maintain trust in digital banking. Those that delay could struggle to keep up with increasingly intelligent cybercriminals.